

Money Manager (Remove Ads)
Realbyte Inc.
- 4.7
- 286.00 Reviews
- 100.00K
- Downloads
- $5.99
- Price
Screenshots
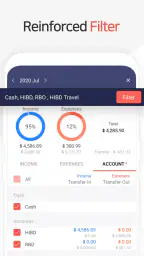
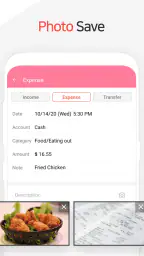
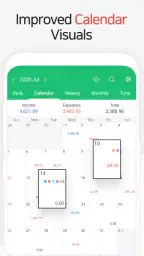
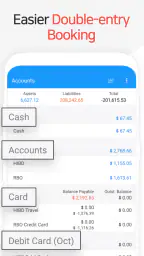
Money Manager (Remove Ads) Pros and Cons
Pros
- User-friendly interface for easy navigation
- Supports multiple currencies for global use
- Customizable categories for expense tracking
- Data backup and restoration via cloud services
- No ads for an uninterrupted experience
Cons
- Limited features in free version
- Some users report sync issues
- Occasional bugs in app updates
- No investment tracking option
- Requires manual data entry
 Analysis by All-app
When I’m trying to work out why my money disappears between paydays, I don’t need another account dashboard full of information I never use. I need a quick way to record what came in, what went out, and whether the pattern is changing. That is the practical role I’d give Money Manager (Remove Ads): a finance app from Realbyte Inc. for keeping personal money records organized. It has a 4.7 average from around 18,000 ratings, and more than 100,000 installs, so it has clearly found an audience among people who want hands-on tracking rather than a financial product that does everything for them.
The important distinction is that recording a transaction is only the start. The value comes when I use those entries to make a small decision: pause a category of spending, plan for an upcoming bill, or check whether I can afford a purchase without relying on memory. This app makes most sense for that kind of steady, personal routine. It is less suited to someone who expects their finances to appear automatically without any regular input.
Start with the money question, not the settings
Before setting up categories or budgets, I’d decide what I want to learn. If the problem is that small daily purchases are hard to remember, the first goal is simply to log them consistently. If I already know where my money goes but want to control one area, a category budget is a better starting point. Trying to organize every detail on day one can turn a useful habit into a chore.
That choice matters because a personal finance tracker is only as helpful as the records entered into it. I would begin with a few categories that match the way I actually spend, rather than building an elaborate system around labels I’ll never use. A category such as groceries is easier to review than a long collection of tiny distinctions, unless those distinctions answer a real question for me.
Getting Started with Money Manager
First things first, downloading and setting up the Money Manager (Remove Ads) app is a breeze. Available on both Android and iOS, it ensures a seamless experience right from the start. As soon as I opened it, I was greeted with a clean and intuitive interface. It’s like the app just gets me, you know? No unnecessary clutter, just straightforward options to manage my finances.
For someone moving from notes or a spreadsheet, I’d treat the first few days as a trial run rather than trying to reconstruct months of spending. Add income and purchases as they happen, then look at the resulting categories. That gives a more honest picture of what the app can do in normal use and makes it easier to spot any category names that need adjusting. The trade-off is clear: a careful setup takes a little thought, but it saves confusion later when a summary groups transactions in a way that doesn’t match my habits.
Features That Make Life Easier
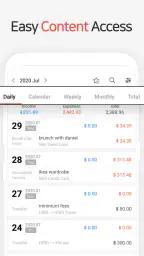
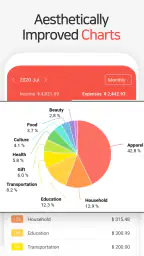
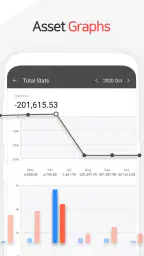
Now, let’s talk about what makes this app a real game-changer. The app allows you to track your expenses and income effortlessly. You can categorize each transaction, which really helps in understanding where your money is going. Plus, the visual graphs are not only super helpful but also quite satisfying to look at. Who knew budgeting could be this fun?
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Another neat feature is the budget setting. You can set monthly budgets for different categories and the app will notify you if you’re getting close to your limit. It’s like having a personal financial advisor, minus the hefty fees. And for those of us who love a good spreadsheet, you can export all your data to Excel. It’s a nerd’s dream come true!
The most useful way to combine those tools is to let a graph point to a question, then check the transactions behind it. A high total for eating out, for instance, can be a prompt to look at which days or situations led to it, rather than a reason to make a budget unrealistically strict. I’d use a category limit as a nudge, not as a verdict on whether I’ve been “good” or “bad” with money.
For a practical weekly routine, I’d enter purchases close to when they happen, check the category totals once or twice, and use the end-of-month view to choose one change for the next month. If I’m always surprised by transport costs, I can adjust that category instead of cutting an unrelated one. This is a more useful outcome than merely collecting records: the app can help turn a vague feeling about spending into a specific adjustment.
Turning a normal day into a useful record
Imagine I buy groceries after work, pay for a ride, and then pick up a coffee. If I enter those items while the day is still fresh, I’m less likely to forget the small purchase that makes my weekly total feel unexpectedly high. At the end of the week, I can compare categories and see whether the pressure came from one unusual trip or from several small routines. That distinction changes what I do next: a one-off cost may need no budget change, while a repeated pattern might.
A non-obvious habit that helps is to settle on a rule for ambiguous purchases before they accumulate. For example, I can consistently put household supplies in one category instead of sometimes treating them as groceries and sometimes as shopping. The exact labels matter less than using them the same way. Consistent records make the graphs and category budgets more meaningful; inconsistent records can make even a polished summary misleading.
I’d also avoid setting every budget at the amount I wish I spent. A limit should be useful for noticing a trend, and an unrealistically low figure can make the warning feel constant and easy to ignore. A better first month is to observe what I actually spend, then make a modest adjustment where I have room to change. That turns the budget from a punishment into a planning tool.
Security and Syncing
In today’s digital age, security is a big concern, and thankfully, Money Manager takes it seriously. The app comes with a passcode lock feature, ensuring that only you have access to your financial data. Plus, it offers syncing across devices through cloud storage, so you can manage your finances on the go, whether you’re using your phone, tablet, or even your desktop.
The cloud backup is a lifesaver if you switch devices or accidentally delete the app. Your data remains safe and sound, ready to be restored whenever you need it. It’s peace of mind at its finest.
For a person who records spending on a phone but likes to review figures on a larger screen, having a cross-device handoff can be convenient. I would still make that workflow deliberate: enter transactions in one place, then check that the records are available where I expect them before relying on a second device. A passcode lock is also a sensible basic safeguard if I share a phone or leave it unattended, though it doesn’t replace careful habits around the device itself.
Exporting to Excel offers a different kind of handoff. It is helpful when I want to sort or inspect records outside the app, or keep a working copy for my own analysis. But exporting is not the same as having an automatically maintained spreadsheet: I need to remember when I want a fresh file and how I’ll use it. For someone who enjoys building custom calculations, that flexibility is a plus. For someone who wants a ready-made financial report with no follow-up work, it may feel like an extra step.
Where a manual tracker helps—and where it doesn’t
Compared with the usual alternatives, this approach sits between a paper notebook and a bank app that focuses on showing account activity. A notebook is flexible but takes more effort to total and compare. A bank’s own tools may be convenient for transactions in that account, but they are not necessarily organized around the categories and personal budgets I want to review. Money Manager’s appeal is the deliberate record: I can shape categories and use the app’s visual summaries, provided I keep entering information.
That same manual involvement is the main limitation. If I routinely forget cash purchases, delay entering transactions, or want all spending gathered without effort, a tracker that relies on my attention can quickly become incomplete. The graphs may look convincing even when a week of entries is missing, so I would not treat a partial record as a reliable account of my finances. For someone who values automatic account aggregation above control over personal categorization, a different finance app may be the better fit.
It is also not a substitute for every money tool. I would choose it to understand day-to-day income and spending, not because I expect it to make financial decisions for me. A budget notification can draw my attention to a category, but I still need to decide whether the spending was necessary and what adjustment is realistic. The app is most effective when I bring that judgement to the review instead of expecting a chart to supply it.
Choosing the right version and routine
The ad-free version is a paid option: the app costs $5.99, with in-app purchases listed from $2.49 to $19.99 per item. I see the remove-ads choice as a question of preference, not a requirement for budgeting itself. If interruptions bother me while I’m entering several transactions or checking a monthly summary, paying for an ad-free experience may feel worthwhile. If I’m still unsure whether I’ll maintain the habit, I’d first decide whether the workflow suits me before treating the purchase as essential.
The app is rated Everyone and supports Android 6.0 or later. It has been available since April 5, 2012, and its current version is 4.10.3 GP. Those details make it easier to judge basic compatibility, but the more important question is whether my own device and routine make frequent entries convenient. A finance tracker that I only open at the end of the month is unlikely to give me the same useful picture as one I check in short, regular sessions.
I’d recommend it most to people who like seeing their spending organized into categories and are willing to maintain the record themselves. It can suit a student keeping an eye on everyday purchases, a household member tracking a personal share of common costs, or anyone trying to understand why a monthly budget keeps drifting. It is less compelling for a person who wants investment planning, automatic financial management, or a completely hands-off view of several accounts. The right choice depends less on how attractive the graphs look and more on whether entering transactions fits into daily life.
Why Go Ad-Free?
Let’s be honest, ads can be pretty annoying, especially when you’re trying to focus on something important like your finances. The ad-free version of Money Manager is worth every penny. It keeps the app running smoothly, without any interruptions, allowing you to concentrate on what truly matters – managing your money effectively.
Plus, the developers deserve a shoutout for offering an ad-free option. It shows they care about the user experience, and who doesn’t appreciate that?
After using a routine like this, I’d judge success by whether I can answer a useful question at the end of the month: which category changed, what caused it, and what do I want to do next? If I can answer that from a reasonably complete set of entries, the app has earned its place in my routine. If I keep postponing input, the problem is probably not a lack of charts; it is a mismatch between manual tracking and the way I handle money.
So, if you’re on the hunt for a reliable and user-friendly finance app, give Money Manager (Remove Ads) a try. It’s like having a financial buddy right in your pocket, ready to help you conquer the world of budgeting and expense tracking.
Happy budgeting!
Frequently Asked Questions
What features does Money Manager (Remove Ads) offer?
Money Manager (Remove Ads) provides comprehensive features to manage your finances effectively. It includes expense tracking, budget planning, financial reports, and account management. The app also allows for syncing with bank accounts and exporting data in various formats. Additionally, it offers secure backup options and personalized financial insights without the interruption of ads.
Is Money Manager (Remove Ads) safe to use for tracking my financial data?
Yes, Money Manager (Remove Ads) prioritizes your data security. The app uses robust encryption protocols to protect your financial information. It also provides options for secure cloud backups and data recovery. Users can set up password protection or biometric authentication to enhance security, ensuring that only authorized individuals can access sensitive data.
How user-friendly is the Money Manager (Remove Ads) app?
Money Manager (Remove Ads) is designed with user-friendliness in mind. The app features an intuitive interface that is easy to navigate, making it accessible for both beginners and advanced users. It provides straightforward tutorials and user guides to help you get started. Customizable settings and a responsive support team further enhance the user experience.
Does Money Manager (Remove Ads) support multiple currencies and languages?
Yes, the app supports multiple currencies and languages, making it versatile for users around the world. It automatically converts currencies based on real-time exchange rates and allows you to manage accounts in different currencies. The app's multilingual interface caters to a global audience, offering language options such as English, Spanish, French, and more.
What distinguishes Money Manager (Remove Ads) from other finance apps?
Money Manager (Remove Ads) stands out due to its ad-free experience, allowing users to focus solely on managing their finances without distractions. Unlike many free apps that rely on ads, this version ensures a seamless experience. It also offers comprehensive features, strong data security, and excellent customer support, making it a preferred choice for serious financial management.


